

MoBill Budget and Reminder
by MoBill Apps
4.0
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.0
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
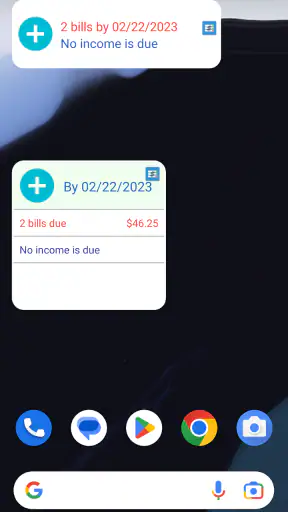
 Analysis by Getfullapps
I approached MoBill Budget and Reminder as a practical personal-finance tool rather than a full banking replacement. Its purpose is straightforward: help me keep track of money coming in, regular bills, and the spending decisions that usually get forgotten between paydays. After using it as a lightweight budgeting companion, I found that its biggest strength is not flashy presentation but the way it can turn scattered financial chores into a repeatable routine.
This is a free finance app from MoBill Apps, available for everyone and supported on Android 8.0 or later. It has been around since February 28, 2011, and the current version is 5.3.1. With more than 500 thousand installs, it is clearly aimed at ordinary people who want a simple way to stay aware of their commitments without immediately moving to a complicated financial-management system.
How I built a dependable everyday workflow
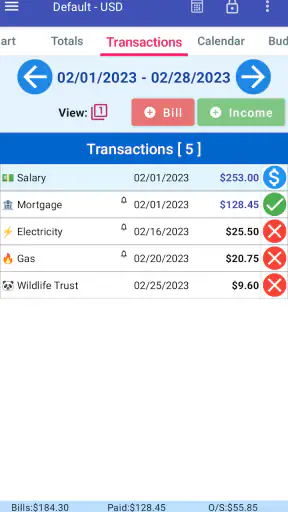
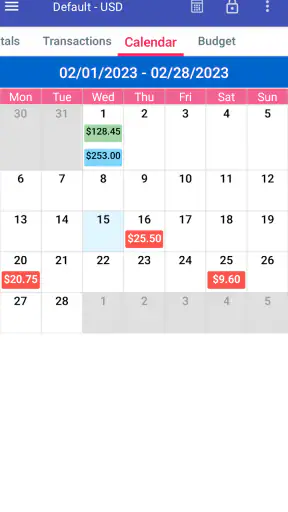
The most useful way to start is not by trying to record every coffee or impulse purchase. I first treated the app as a calendar for financial obligations. I entered the payments that could cause real trouble if forgotten: rent, utilities, subscriptions, insurance, loan repayments, and other recurring commitments. That gave me a clearer picture of what my available money needed to cover before I thought about flexible spending.
That order matters. Many budgeting apps encourage users to begin with categories and detailed expense tracking, but a reminder-centered tool works better when the first job is protecting the essentials. Once the fixed commitments are visible, I can decide how much room remains for groceries, transport, entertainment, and unexpected costs. The result is less ambitious than a full accounting system, but it is often more useful for someone whose main problem is losing track of due dates.
I also found it helpful to separate predictable bills from irregular expenses. A monthly payment belongs in one mental group, while an annual renewal or occasional school cost belongs in another. If everything is treated as an ordinary monthly expense, the quieter months can look healthier than they really are. I use the app as a prompt to remember those less frequent obligations and then keep a small note outside the normal weekly spending plan for them.
A realistic example is a payday routine. On payday, I check the upcoming reminders, identify which payments fall before the next payday, and compare that total with the money I can safely use. I do not need to open the app every time I buy something. I only need a short review at the right moment. That makes the system easier to maintain than a detailed tracker that demands constant attention and is eventually abandoned.
This approach also answers an important question: is it necessary to connect a bank account? For the way I use MoBill Budget and Reminder, no. I prefer manually entering the information that matters to me, because it keeps the app focused on planning rather than asking it to become a complete record of every transaction. People who want automatic bank synchronization, investment monitoring, or a consolidated financial dashboard will probably find this approach too limited.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The app is particularly comfortable for users who already know their regular payments and want a visible reminder system. It is less suitable for someone who needs precise reconciliation against a bank statement. Manual entry gives me control, but it also means accuracy depends on my own discipline. If I forget to add a new subscription or change an amount after a price increase, the plan becomes outdated without the app being able to correct it for me.
Settings that deserve attention before daily use
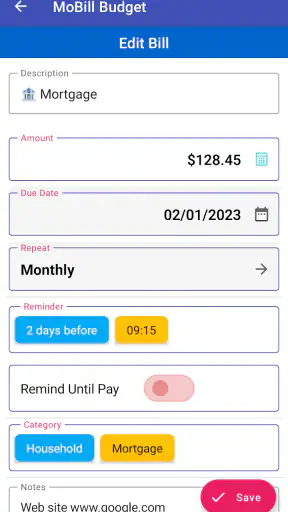
The first settings I would review are the reminder behavior and the timing of each recurring item. A reminder that arrives on the due date may be technically correct but practically late, especially when a payment needs a transfer, a trip to the bank, or a few days for processing. I prefer to give myself enough notice to act rather than simply be told that something is due now.
It is also worth checking how recurring amounts are handled in your own routine. Some bills stay stable, while others change from month to month. I would not blindly assume that a repeated entry remains accurate forever. A quick monthly check is a good habit for variable utilities, mobile services, and subscriptions that occasionally change their terms. The app can remind me about the obligation, but I still need to verify the amount.
Another useful decision is how much detail to put into names. A label such as “payment” is too vague when several obligations are scheduled close together. Clear names make a quick glance meaningful: a bill should be identifiable without opening several entries to remember what each one means. I find that descriptive labels reduce the chance of paying the wrong item or overlooking a smaller charge hidden among larger ones.
I would also avoid creating an elaborate structure on the first day. The temptation is to enter every possible category, every occasional purchase, and every imagined future expense. That creates administrative work before the basic habit is established. I get better results by adding only the information I will actually review. Once the routine feels natural, I can expand it carefully instead of turning the app into another chore.
For people sharing household responsibilities, naming becomes even more important. A reminder should make it obvious what needs attention and, if relevant, who normally handles it. MoBill Budget and Reminder is not a replacement for a conversation about shared money, but a clear list can make that conversation more concrete. It is easier to discuss an upcoming payment when the obligation is visible than when it exists only in one person’s memory.
The app is free to download, although in-app purchases range from $2.50 to $10.99 per item. That makes it sensible to begin with the basic workflow and decide later whether the paid options fit your needs. I would not pay simply because a finance app feels incomplete after a rushed setup. First I would test whether the reminder habit actually prevents missed payments and improves my awareness. If it does, optional spending may be easier to judge.
Faster patterns for people who dislike bookkeeping
My favorite efficiency trick is to use a short weekly review instead of constant checking. I choose one consistent moment, look ahead at the next group of obligations, and update anything that has changed. This keeps the app useful without making it the center of my day. The key is repetition: the value comes from returning to the same small process, not from entering an enormous amount of information once.
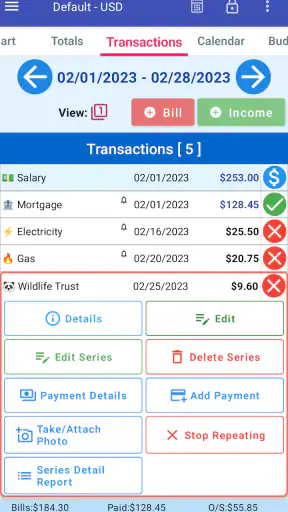
A second pattern is to enter recurring items in batches. When I am setting up a new budget period, I add the known commitments together and then review them as a group. This is faster than remembering one bill today, another tomorrow, and a third after it has already been missed. It also exposes timing problems: several payments may cluster in the same week even if their individual amounts look manageable.
I would use the app differently for fixed and flexible spending. Fixed items deserve dependable reminders. Flexible spending deserves a limit that I can understand without pretending it is perfectly predictable. If I try to model every small purchase with exact precision, the system becomes fragile. Instead, I use the reminders to protect the fixed commitments and a broader spending check to keep discretionary money from quietly disappearing.
There is also a useful distinction between “remembering” and “affording.” A reminder can tell me that a payment is coming, but it cannot make the money available. I therefore review upcoming obligations before spending a larger amount, not after. That simple change prevents the common mistake of treating the current account balance as fully available when part of it already belongs to future bills.
For annual or irregular expenses, I use the reminder as a trigger for preparation rather than as a last-minute alarm. When an infrequent payment appears on the horizon, I can start setting money aside earlier. This is one of the more valuable uses of a basic finance app because the problem is often not the size of the expense but the surprise. A timely prompt turns an unpleasant shock into a planned task.
Another practical habit is to clean up old entries. A discontinued subscription or changed service should not remain among active reminders simply because it was once useful. Clutter makes every future review slower and reduces trust in the list. I would rather have a smaller, current set of commitments than a historical archive that forces me to interpret what still applies.
Where the simple approach reaches its limits
The same simplicity that makes the app approachable also defines its limits. I would not choose it as my only tool if I needed detailed reports, automatic transaction importing, investment views, debt projections, or sophisticated household collaboration. Those tasks call for a broader financial platform or a spreadsheet with more flexible formulas. MoBill Budget and Reminder is strongest when the job is keeping a practical handle on planned money and due dates.
It also depends heavily on manual maintenance. A reminder is only as reliable as the information behind it. If a bill changes, a payment is canceled, or a new recurring charge appears, I have to update the system. That is not a flaw for everyone; some people prefer deliberate control. But users expecting the app to discover changes automatically may become frustrated quickly.
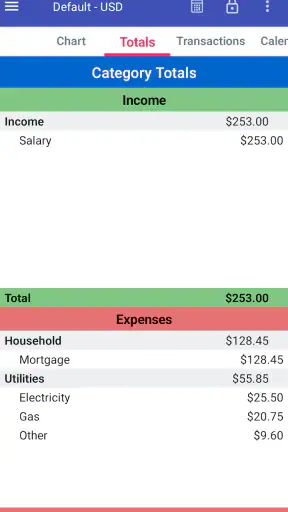
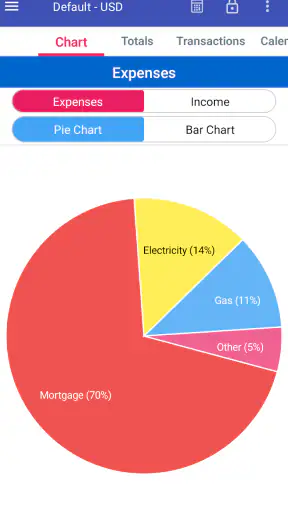
The interface may also feel less satisfying to people who want visual motivation. Some budgeting tools are built around colorful charts, spending trends, and detailed category breakdowns. Here, I would focus less on entertainment and more on whether the information helps me make a decision. If charts are what keep you engaged with your finances, a more visual alternative may be a better fit.
Privacy-minded users may appreciate the manual style because it does not require me to turn the app into a connected financial hub. At the same time, manual control is not the same as complete security assurance, and I still would not enter sensitive information that is unnecessary for budgeting. I keep labels practical and avoid treating a reminder list as a place for confidential account details.
The age rating of Everyone makes the app approachable for a wide range of users, including someone learning to manage household bills for the first time. Still, accessibility in the rating does not remove the need for financial judgment. A beginner may benefit from starting with only a few essential reminders and learning the routine before attempting a full budget. The app can support the habit, but it cannot decide which goals or trade-offs matter most to each household.
Its average rating is 4.0 from around 3.8 thousand ratings, with roughly 1.6 thousand written reviews. I read that as a sign of a generally useful but not universally ideal tool. That matches my experience: the app makes sense when I want a focused reminder and budget companion, but its appeal decreases as my requirements move toward automation and deep analysis.
My verdict after turning it into a repeatable habit
After using MoBill Budget and Reminder with a simple routine, I see it as a good fit for people who want to stop forgetting bills without committing to a demanding financial-management system. Its strongest use is the combination of clear recurring entries, sensible advance reminders, and a short weekly review. Those three pieces are enough to make upcoming obligations more visible and reduce the mental load of remembering everything unaided.
I would recommend it to a student managing regular payments, a household that needs a shared reminder habit, or anyone whose budget problem is mainly timing rather than complex analysis. It can also suit experienced users who deliberately prefer manual control and want a lightweight layer between their bank balance and their spending decisions. The free starting point makes it easy to test that workflow before considering any in-app purchases.
I would skip it if automatic bank feeds, advanced reports, investment tracking, or detailed transaction categorization are non-negotiable. In those cases, a full budgeting platform will save more work in the long run, even if it takes longer to learn. I would also avoid relying on it as a substitute for checking actual account balances and statements. A reminder system supports financial awareness; it does not verify that a payment completed.
My practical advice is to begin with the obligations that would cause the most stress if forgotten, give each one a clear name, schedule reminders early enough to act, and review the list once a week. Add complexity only when it solves a real problem. Used that way, MoBill Budget and Reminder stays focused, understandable, and genuinely helpful. Its real advantage is not doing everything, but making one important financial habit easy to repeat.
Pros
- Simple interface makes tracking bills and spending quick.
- Custom reminders help reduce the risk of missed payments.
- Useful recurring bill support for regular monthly expenses.
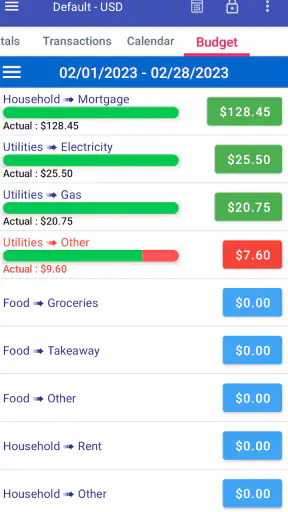
- Budget categories make it easier to monitor spending habits.
- Can improve awareness of upcoming financial commitments.
Cons
- May require regular manual updates for accurate information.
- Limited automation compared with full-featured banking apps.
- Some advanced tools may be restricted behind in-app purchases.
- Notification reliability can depend on device settings.
- Not ideal for users seeking investment or detailed financial analysis.
FAQs for MoBill Budget and Reminder
What is MoBill Budget and Reminder used for?
MoBill Budget and Reminder is designed to help you organize personal finances by recording income, expenses, bills, and payment reminders in one place. After setting up your recurring obligations, you can monitor upcoming due dates and review spending activity more easily. It is especially useful for users who want a straightforward overview of monthly commitments rather than a complicated investment or banking platform.
Can MoBill Budget and Reminder track recurring bills and payment due dates?
Yes, recurring bills and reminders are one of the app’s main purposes. You can enter regular obligations such as rent, utilities, subscriptions, loans, or insurance and assign dates, amounts, and repeat intervals. The reminder feature can help you avoid forgetting payments, although notifications may depend on your device settings, battery restrictions, and whether the app is allowed to run in the background.
Does MoBill Budget and Reminder connect directly to my bank account?
MoBill Budget and Reminder should not be treated as a full bank-connection or automatic transaction-import service unless the version available on your device specifically provides those features. In many cases, users manually enter or update financial information. This can require more effort, but it also gives you greater control over what is stored and lets you keep the app focused on budgeting and reminders instead of sharing banking credentials.
Is MoBill Budget and Reminder suitable for managing a household budget?
The app can be useful for individuals, couples, or households that want to list regular income, expenses, and upcoming bills. It works best when everyone agrees on how categories and shared payments will be recorded. Before relying on it for complex family finances, check whether the current version supports multiple users, account synchronization, backups, or data export, because these options can vary by platform and app release.
What should I check before downloading MoBill Budget and Reminder?
Before installing MoBill Budget and Reminder, review the supported Android or iOS version, storage requirements, privacy policy, and available backup options. Also check whether the features you need—such as recurring reminders, currency support, reports, synchronization, or export—are included without restrictions or require an in-app purchase. Finally, confirm that notifications are reliable on your device, since reminders are only useful when they appear on time.

MoBill Budget and Reminder
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@mobillbudget.com, visit http://www.mobillbudget.com, or review their http://www.mobillbudget.com/privacy.










